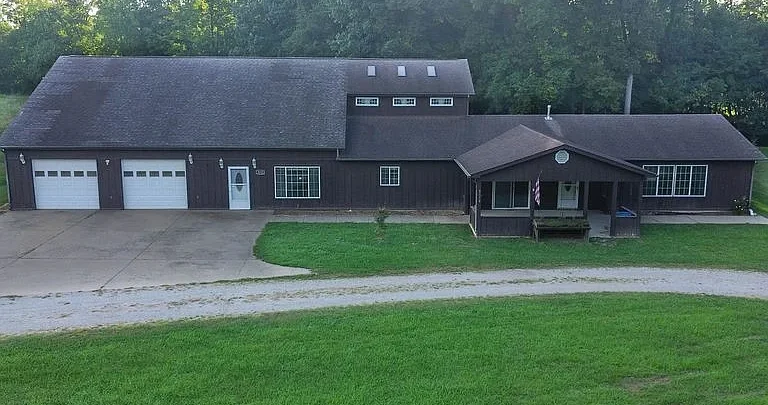
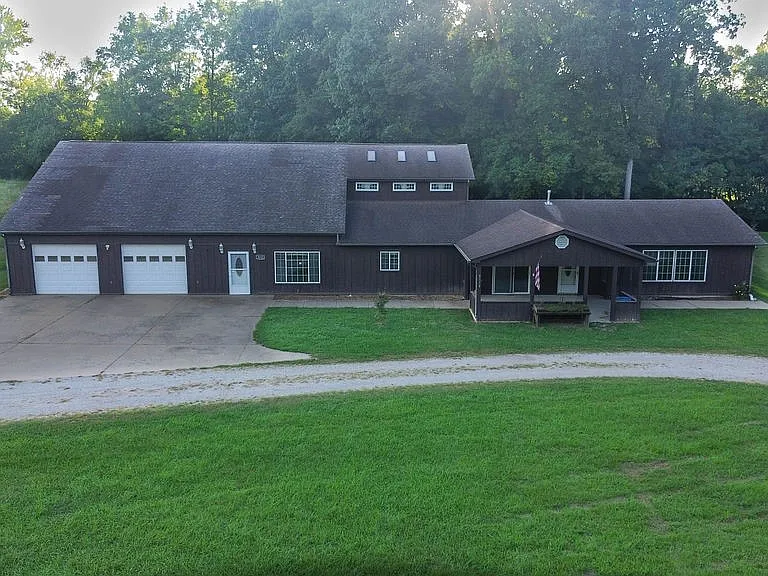
A bank-owned 1990 home with more than 4,400 square feet on 3.02 acres in Danville, Illinois, with a sunroom, rec room, upstairs primary suite, and bonus room, sold as-is and listed at $180,000.
It is not every day you find more than 4,400 square feet of living space on three acres for under $200,000.
This home at 3115 E Voorhees St in Danville, Illinois, offers exactly that.
Built in 1990, it includes four bedrooms, three full bathrooms, a large living room, a spacious rec room, a sunroom, an upstairs primary suite with a soaking tub, and a flexible bonus room. It also sits in the Bismarck school district.
There is an important catch. The property is lender-owned and being sold as-is, with the bank making no representations or warranties.
That combination of size, land, and price makes it worth a close look, but it also makes careful due diligence essential. Below, we walk through every part of this property and the questions any buyer should ask before making an offer.
Property Overview
- Address: 3115 E Voorhees St, Danville, IL 61834
- List price: $180,000
- Bedrooms: 4
- Bathrooms: 3
- Living area: 4,455 square feet
- Year built: 1990
- Lot size: 3.02 acres
- Main level: living room, rec room, kitchen, dining room, sunroom, 3 bedrooms, 2 full baths, laundry
- Upper level: primary suite with soaking tub, separate shower, multiple closets, and a bonus room
- School district: Bismarck
- Seller: lender-owned, sold as-is
The Location: Danville, Illinois
Danville is the largest city in Vermilion County, in east-central Illinois near the Indiana state line.
The area is known for its affordable housing, which is part of why a home this size can carry such a modest price tag. Buyers get far more space and land for their money than they would in larger Illinois metro areas.
The listing notes the home falls in the Bismarck school district. Buyers should verify school boundaries directly with the district, since assignments can change.
What It Means to Buy a Bank-Owned Home
This property is lender-owned, sometimes called a real estate owned or REO property.
That usually means the home went through foreclosure and the bank now owns it. Banks generally want to sell these properties quickly, which can create opportunities for buyers.
However, bank-owned sales are different from typical sales in several ways:
- The bank has usually never lived in the home and knows little about its history.
- Sellers like this typically provide no disclosures about past problems.
- The home is sold as-is, so the bank will not make repairs.
- Bank contracts often include their own addenda with specific terms and deadlines.
- Homes may have sat vacant for some time, which can lead to hidden issues.
None of this means the home is a bad buy. It simply means buyers need to do their own homework thoroughly.
The Land: Just Over Three Acres
The home sits on 3.02 acres.
That is a substantial amount of land, offering room for gardens, play areas, pets, a workshop, or simply open space and privacy.
Buyers should walk the property to see how the land is laid out, how much is open lawn versus trees, and how water drains across it.
The Living Room
The first floor features a large living room.
In a home of this size, a big main living space gives the household a comfortable place to gather. It can easily handle a large sectional, family movie nights, and holiday gatherings.
The Rec Room
A spacious rec room offers a second gathering area on the main level.
Having two large living spaces gives families flexibility. One can serve as a quieter sitting room while the other becomes a game room, playroom, or media room.
The Kitchen
The kitchen has newer appliances and opens to the dining room.
Newer appliances are a welcome feature in a bank-owned property, where appliances are sometimes missing or not working. Buyers should confirm that the appliances are still in the home and test them during inspection.
The open connection to the dining room makes the space practical for everyday meals and easy entertaining.
The listing does not describe the cabinets or countertops, so buyers should look at their condition during a showing.
The Dining Room
The dining room connects directly to the kitchen.
That layout keeps meals social, allowing the cook to stay part of the conversation. It also makes serving large family dinners much easier.
The Sunroom
One of the main-level bedrooms sits off the sunroom.
The listing suggests this arrangement could work as a home office, sitting room, relaxing retreat, or guest quarters.
A sunroom adds natural light and a pleasant spot to enjoy views of the acreage. Buyers should ask whether the sunroom is heated and cooled, or whether it is a three-season room. That affects both comfort and how much of the square footage is year-round living space.
The Main Level Bedrooms
Three bedrooms are on the main level.
This is a valuable layout. It allows single-level living for anyone who prefers to avoid stairs, while the upstairs primary suite offers a private retreat.
The bedroom off the sunroom could be especially useful for guests, extended family, or a dedicated work-from-home space.
The Main Level Bathrooms and Laundry
Two full bathrooms and the laundry area complete the main level.
Main-level laundry is a feature many buyers specifically look for. Two full baths on this floor also mean the three main-level bedrooms are well served.
Buyers should check for leaks, water damage, and fixture condition in both bathrooms, which is especially important in a home that may have been vacant.
The Upstairs Primary Suite
The upper level is dedicated to the primary suite.
It features a large bedroom with multiple closets, giving plenty of space for clothing and storage.
Having the primary suite on its own floor creates privacy and separation from the rest of the household, which many buyers find appealing.
The Primary Bathroom
The private primary bathroom includes both a soaking tub and a separate shower.
That combination is a popular feature, offering a quick shower for busy mornings and a relaxing soak at the end of the day.
Ask the inspector to check the tub, shower, and surrounding areas for any signs of leaks or water damage.
The Bonus Room
A bonus room sits upstairs alongside the primary suite.
The listing suggests it could become an office, dressing room, hobby space, or additional living area. Other possibilities include a nursery, reading room, home gym, or craft room.
Flexible rooms like this are a big part of what makes larger homes so adaptable as needs change over time.
Roof
The listing does not mention the roof’s age or condition.
For a 1990 home, the roof may have been replaced at least once, or it may be due. A large home also means a large roof. Buyers should have a roofer evaluate it, since replacement can be a major cost.
Foundation and Structure
The listing does not describe the foundation.
Buyers should ask the inspector to check for cracks, settling, and signs of water intrusion. Bank-owned homes that sat vacant may have had unnoticed leaks or moisture problems.
HVAC
The heating and cooling system is not described.
A home of more than 4,400 square feet may use more than one system. Ask about type and age, and have an HVAC technician inspect them. If the home has been vacant during winter, check whether it was properly winterized.
Plumbing and Winterization
Vacant bank-owned homes in cold climates are often winterized, meaning the water is shut off and lines are drained to prevent freezing.
Buyers should ask whether the home was winterized and request that utilities be turned on for inspection. A pressure test of the plumbing can reveal leaks or freeze damage that would otherwise go unnoticed.
Utilities
Confirm whether the home is on public water and sewer, or on a well and septic system.
On a three-acre lot, private systems are possible. If there is a well, test the water. If there is a septic system, have it inspected, since a vacant property may not have been maintained.
As-Is Means As-Is
The listing states that the property is being sold as-is and that U.S. Bank National Association is making no representations or warranties.
That means the buyer takes the home in its current condition. Anything discovered during or after inspection becomes the buyer’s responsibility.
Buyers should budget a cushion for unexpected repairs, often recommended at ten to twenty percent of the purchase price for older or vacant homes.
Insurance Considerations
Homes that have been vacant can be harder to insure.
Buyers should get insurance quotes early and disclose the property’s status. Roof age and the condition of major systems will also affect pricing.
Financing Options
Unlike some bank-owned sales, this listing notes the seller may have financing options available.
Several loan types could work, depending on the home’s condition:
Conventional loans are common for buyers with good credit. The home will need to meet lender condition standards.
FHA loans allow lower down payments, but the home must pass FHA property requirements. Any major safety or condition issues may need to be fixed before closing, which can be tricky in an as-is sale.
VA loans allow eligible veterans to purchase with no down payment, subject to the home meeting VA standards.
USDA loans are designed for eligible rural areas. A three-acre property outside the city center may qualify. Buyers should check the exact address on the USDA eligibility map.
FHA 203k and Fannie Mae HomeStyle renovation loans let buyers finance both the purchase and needed repairs. These can be especially useful for as-is homes that need work to meet lending standards.
Cash buyers often have an advantage in bank-owned sales, since they can close faster and avoid appraisal issues.
Who This Home Is For
This home suits several types of buyers.
Large families get four bedrooms, three baths, and multiple living spaces.
Remote workers get a sunroom-adjacent bedroom and a bonus room for offices.
Value-focused buyers get a huge amount of house and land for the price.
Hands-on buyers comfortable with some risk get the chance to build equity through repairs and updates.
Owner-Occupant Potential
As a primary residence, this home offers space that is hard to find at this price point.
Main-level living with three bedrooms, plus a private upstairs suite, makes it adaptable for families of all sizes and stages.
Rental Potential
A four-bedroom home on three acres could appeal to long-term renters, especially larger families.
Investors should estimate repair costs carefully, research local rents, and confirm any rental registration requirements in Danville or Vermilion County.
Possible Future Improvements
- Updating flooring and paint throughout
- Refreshing the kitchen cabinets and countertops
- Converting the bonus room into a home office or nursery
- Adding heating and cooling to the sunroom for year-round use
- Building a detached garage or workshop on the acreage
- Adding a large deck or patio overlooking the yard
- Planting a garden or small orchard
Questions to Ask Before Making an Offer
- How long has the home been vacant?
- Was it properly winterized?
- Can utilities be turned on for inspection?
- How old are the roof, HVAC, and water heater?
- Is the home on public water and sewer, or well and septic?
- Are the newer appliances still in the home?
- Is the sunroom heated and cooled?
- Are there any open code violations or liens?
- What are the property taxes?
- What terms are in the bank’s contract addendum?
Inspection Is Essential
With a bank-owned, as-is sale, inspection is the most important step.
Buyers should get a full home inspection, plus specialized inspections as needed, such as roof, HVAC, sewer or septic, and well water testing. A mold assessment may also be wise if there are any signs of moisture.
Get contractor estimates for any repairs before your inspection period ends, so you know your true total cost.
The Price in Context
At $180,000, the home works out to roughly $40 per square foot.
That is a very low price per square foot, even for the Danville area, and it includes more than three acres of land.
The real number to consider is the purchase price plus repairs. Buyers should compare that total against recent sales of similar-sized homes on acreage nearby.
Final Thoughts
This Danville home offers a rare combination of space, land, and price.
More than 4,400 square feet, four bedrooms, three full baths, a sunroom, a rec room, a private primary suite with a soaking tub, a bonus room, and just over three acres in the Bismarck school district.
Because it is bank-owned and sold as-is, buyers must do their homework carefully. But for the right buyer, this could be a chance to get a lot of home for the money.
Would you live here?

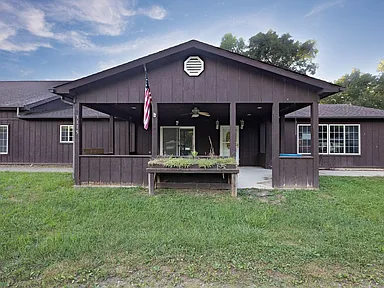


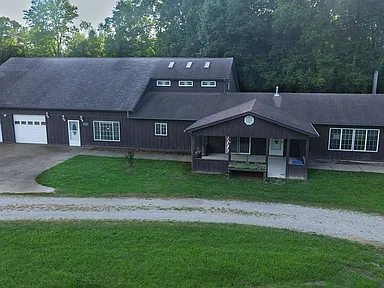
View the full listing on Zillow: 3115 E Voorhees St, Danville, IL 61834
Our website is designed for informational and entertainment purposes only. We are not a real estate brokerage or licensed contracting service. We operate solely as an independent blog, curating interesting houses, DIY guides, and practical home tips found across the internet. All decisions related to real estate transactions or home renovations should be made in consultation with licensed professionals. We do not guarantee the ongoing accuracy or availability of external property listings, as market statuses change rapidly. Please use our content at your own discretion.